The reasons for raising rates and for borrowing more are different
The European Central Bank's account of its September monetary policy meeting, released on October 8, said the energy shock was lasting longer than expected and the inflation outlook had deteriorated. All participants supported the proposal to raise policy rates by one step.
Official source fact · EvidenceThe account said long-term euro area interest rates had risen since the July meeting. These rates help gauge the cost of borrowing over longer periods. Their movement also reflected global financial markets, debt issuance and the fiscal outlook.
Official source fact · EvidenceA rate decision alone therefore cannot tell us how businesses and households are doing. We need to examine how energy costs feed into prices, who faces higher financing costs first and what borrowed money is used for.
SignalTrace interpretation · EvidenceScope of this explanation
This is an explanatory sequence, not a measurement of the causal effect or time lag at each stage.
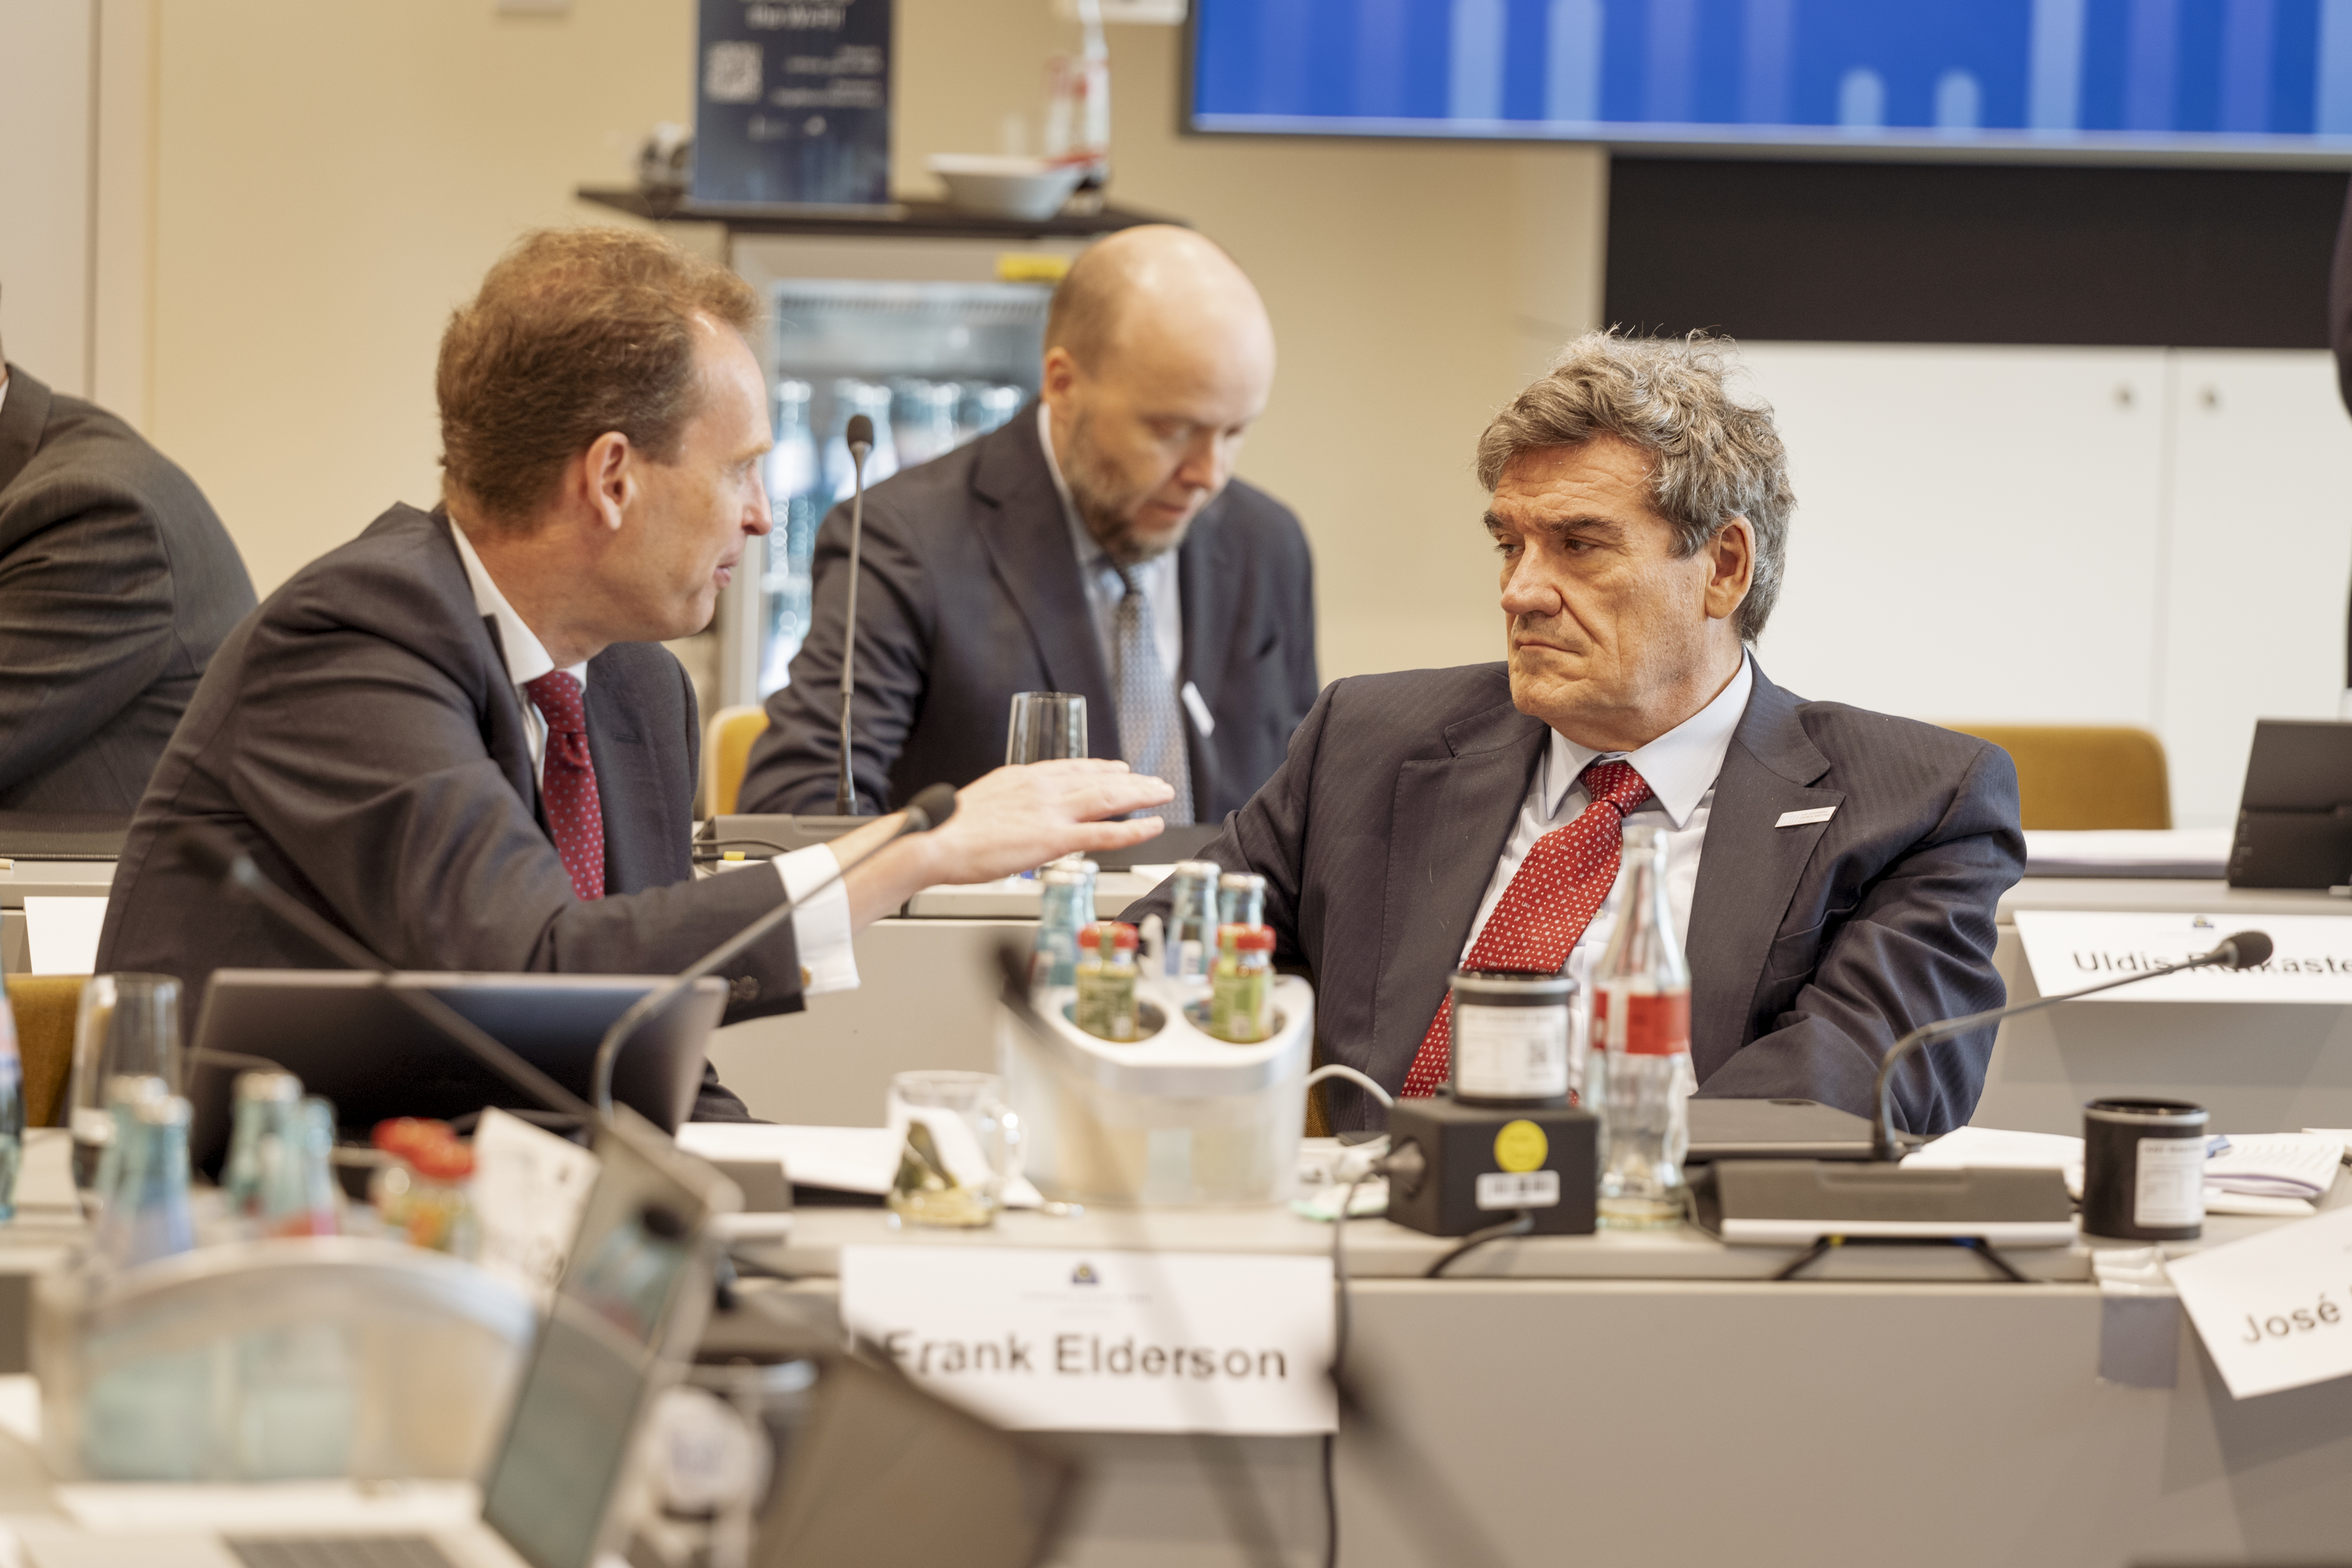
The September monetary policy meeting discussed in this article. This official ECB press photograph was taken in Berlin on September 10, 2026, not on October 8 when the meeting account was released.
Photo: ECB / Maurice Weiss / Ostkreuz · 2026-09-10 · ECB press photograph terms of use. Original photograph supplied by the ECB, shown at its original aspect ratio without cropping or retouching.
Official ECB account of the meeting shown in the photograph →The same increase in lending can reflect different circumstances
More business borrowing does not necessarily mean stronger investment in equipment. The account said firms might also have borrowed to cover higher input costs. Working capital means the money needed to keep a business operating, including spending on materials.
Official source fact · EvidenceBusiness lending rates were 3.6% in May 2026, 3.8% in June 2026 and 3.8% in July 2026.
Official source fact · EvidenceScope of this explanation
These are May–July figures in the meeting account released on October 8, 2026. They are not October interest rates or loan balances. Changes in growth rates are measured in percentage points, not percent.
Year-on-year growth in bank lending to businesses was 4.0% in May 2026, 4.0% in June 2026 and 4.4% in July 2026. These figures alone cannot establish the purpose of borrowing or a causal relationship between interest rates and lending growth.
Official source fact · EvidenceScope of this explanation
These are May–July figures in the meeting account released on October 8, 2026. They are not October interest rates or loan balances. Changes in growth rates are measured in percentage points, not percent.
Think of borrowing to enlarge a factory, then of borrowing to pay higher material costs while keeping output unchanged. Loans rise in both cases, but they tell different stories about the business.
Illustration · EvidenceScope of this explanation
This is a hypothetical comparison to aid understanding, not an actual case involving a particular company.
Access to funding also differs. The account noted that small and medium-sized enterprises have difficulty accessing private credit and rely much more on bank loans. Private credit is lending from private providers outside the banking system. The discussion was that smaller firms may face credit constraints because switching funding sources is harder than it is for large companies.
Official source fact · EvidenceHousehold lending needs a similar distinction. The account highlighted more loan applications from financially stretched households facing higher living costs. Credit growth in this case may reflect an effort to cope with pressure rather than an improvement in household finances.
Official source fact · EvidenceThe same credit growth, different questions
The meeting account's explanations are shown beside the next questions to check. Each item comes from the article; this is not a measurement of actual borrowing purposes.
| Group | What the meeting account noted | What to check alongside it |
|---|---|---|
| Businesses | The account said firms might also have borrowed to cover higher input costs. Official source fact · Current event · Evidence | Is business loan demand more closely linked to investment or working capital? Follow-up question · Current event · EvidenceScope of this explanationThis is a follow-up observation question, without a probability or price target. |
| Small and medium-sized enterprises | The account noted that smaller firms have difficulty accessing private credit and rely much more on bank loans. Official source fact · Current event · Evidence | This is why lending rates and approvals by company size should be examined alongside investment and working-capital purposes. SignalTrace interpretation · Current event · EvidenceScope of this explanationData on approvals, rates and loan purposes by company size have not yet been linked to this article. |
| Households | The account highlighted more loan applications from financially stretched households facing higher living costs. Official source fact · Current event · Evidence | Does household borrowing reflect room for housing and consumption, or pressure from living costs? Follow-up question · Current event · EvidenceScope of this explanationJudgment about the strength of transmission is withheld until the evidence is assembled. |
Three places to look for signs of pressure
From observed facts to possible effects. Interpretations and outlooks are distinct from established results.
SignalTrace interpretation
First are industries that use substantial fuel and electricity. Persistently high energy costs may feed into intermediate-goods prices and increase the cash firms need between buying materials and receiving payment for products. Producer and intermediate-goods prices must be compared with working-capital demand over the same period to see whether this connection actually appears.
SignalTrace interpretation · EvidenceScope of this explanation
These sources do not establish cost pass-through or company margins in a particular industry.
How might energy costs spread?
This is the transmission hypothesis described in the article. Arrows indicate connections to check, not measured causal effects, magnitudes or time lags.
Start · energy costs
If energy costs remain high
SignalTrace interpretation · Current event · EvidenceScope of this explanation
These sources do not establish cost pass-through or company margins in a particular industry.
Through · intermediate-goods prices
they may feed into intermediate-goods prices,
SignalTrace interpretation · Current event · EvidenceScope of this explanation
These sources do not establish cost pass-through or company margins in a particular industry.
To · working-capital needs
and increase the money firms need between buying materials and receiving payment for their products.
SignalTrace interpretation · Current event · EvidenceScope of this explanation
These sources do not establish cost pass-through or company margins in a particular industry.
SignalTrace interpretation
Next are smaller firms that rely on bank loans. If they need more money to meet costs while lending conditions tighten, production and employment could come under pressure sooner. This is why we need lending rates and approval trends by company size, alongside the split between investment and working-capital borrowing.
SignalTrace interpretation · EvidenceScope of this explanation
Data on approvals, rates and loan purposes by company size have not yet been linked to this article.
SignalTrace interpretation
Finally, households. We need to distinguish borrowing that expands housing and consumption from borrowing that fills a living-cost shortfall, and examine income, spending and arrears together. Differences in pressure across income groups also matter.
SignalTrace interpretation · EvidenceScope of this explanation
This does not establish current burdens for individual households or their distribution across income groups.
July and September are different points in the same episode
The July meeting account, released on August 27, said developments in energy markets and artificial intelligence were affecting financial markets. It also discussed the time needed for an energy shock to spread to other prices and wages, and how subsequent responses would depend on profits and wages.
Official source fact · EvidenceThe September account, released on October 8, cited a longer-than-expected energy shock and a worse inflation outlook as grounds for raising rates.
Official source fact · EvidencePutting the two meetings side by side shows how the context for assessing the shock's persistence changed within the same policy cycle. But energy, inflation and financial conditions changed between meetings, so July's explanation cannot simply be applied to September's outcome. July serves as historical background, not additional evidence of current facts. If subsequent credit data point elsewhere, this comparison should carry less explanatory weight.
SignalTrace interpretation · EvidenceScope of this explanation
The comparison alone cannot estimate policy effects or the size of current financial pressure.
We cannot assume cost pressure has spread to everyone
The account also recorded a view that robust lending growth signaled financial conditions were not yet restrictive. It contained counterevidence too: inflation had not yet spread widely across consumer items after the energy shock, and wage growth was slowing. Evidence of cost pressure must be distinguished from evidence that broad pass-through has already occurred.
Official source fact · EvidenceIf energy costs fall quickly and their effects on wages and services inflation stay limited, the case for prolonged inflation pressure and monetary tightening could weaken. Stable lending conditions and approvals for smaller firms, or improving real incomes and stable household stress indicators, would also warrant lowering the assessed strength of those transmission channels.
SignalTrace interpretation · EvidenceScope of this explanation
These are counterconditions, not a claim that they have already been met.
What this article establishes is the ECB meeting's assessment and discussion. It does not verify individual companies' cash flow, actual borrowing purposes or outcomes for particular households. Total lending alone therefore cannot establish that investment or consumption is strong or weak.
Scope of explanation · EvidenceNext, check both the purpose and terms of borrowing
How much have energy costs fed into intermediate-goods and consumer prices? Check the breadth and persistence of the effects in price data covering the same period.
Follow-up question · EvidenceScope of this explanation
This is a follow-up observation question, not a public forecast with a fixed maturity and settlement rule.
Is business loan demand more closely linked to investment or working capital? Examine lending terms and purposes by company size together.
Follow-up question · EvidenceScope of this explanation
This is a follow-up observation question, without a probability or price target.
Does household borrowing reflect room for housing and consumption, or pressure from living costs? Check whether income, spending and arrears data point in the same direction.
Follow-up question · EvidenceScope of this explanation
Judgment about the strength of transmission is withheld until the evidence is assembled.